Choosing the right Dutch tax adviser is critical for entrepreneurs setting up a BV, establishing a holding structure, and managing ongoing compliance. Schmitz Tax Services provides the in-house quality large companies have, offering a single point of contact for tax returns, bookkeeping, and strategic advice. This guide covers the essential steps for BV formation, the logic behind holding structures, and the administrative requirements for maintaining a compliant Dutch business entity.
BV Formation: Choosing the Right Structure
For many entrepreneurs, the decision between a sole proprietorship (eenmanszaak) and a private limited company (BV) is the first major tax and legal milestone. A BV is a separate legal entity that limits personal liability, which is a significant advantage over a sole proprietorship where personal assets are at risk. The choice of legal form dictates your tax obligations, administrative burden, and long-term financial flexibility.
Legal Form and Liability
Timing the Conversion
Many start as a sole proprietorship to minimize initial costs and then convert to a BV once revenue stabilizes. The timing of this conversion is a tax-critical decision. Converting too early may result in unnecessary administrative costs, while waiting too long can complicate the transfer of assets and liabilities. A tax adviser should analyze your cash flow, profit margins, and growth trajectory to determine the optimal moment for incorporation. At Schmitz Tax Services, the analysis starts from a business point of view, ensuring the structure fits your actual activities rather than just the tax rules.
Director's Salary and Dividends
Once a BV is established, the director must receive a mandatory salary. This salary is subject to income tax and payroll tax. The balance between salary and dividends is a key optimization area. Dividends are taxed differently than salary, and the optimal split depends on your personal income level and the company's profitability. Getting this balance wrong can lead to higher overall tax payments or compliance issues with the Tax Administration.
Holding Structure Setup: When and Why
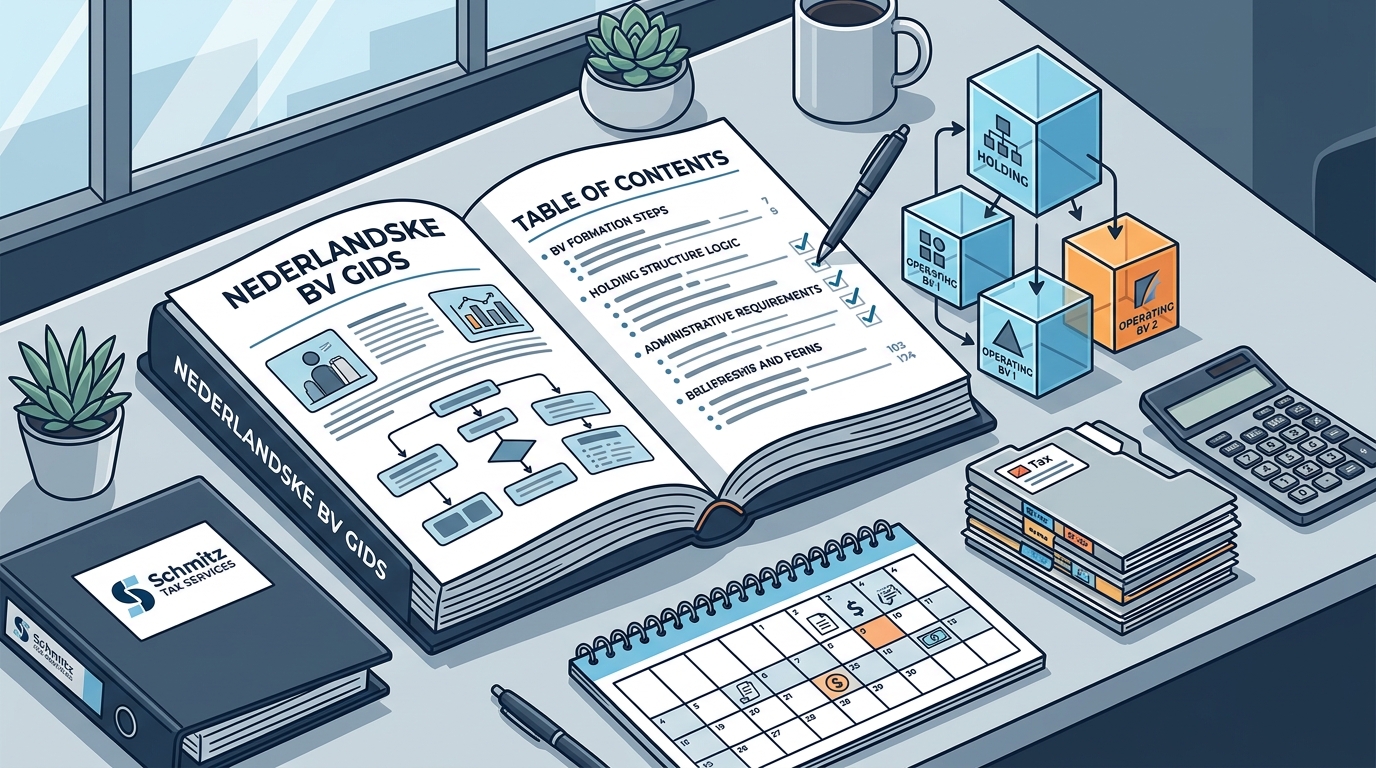
A holding structure involves setting up a parent company (the holding) that owns the shares of one or more operating companies. This is a common strategy for entrepreneurs who plan to build a portfolio of businesses or who wish to protect their assets. The holding company does not typically conduct business itself; it holds shares and manages investments.
Tax Advantages of a Holding
The primary tax advantage of a holding structure is the participation exemption. Under Dutch tax law, dividends received by a holding company from its subsidiaries are generally exempt from corporate income tax. This allows profits to be retained within the holding structure and reinvested without immediate tax leakage. Additionally, the holding structure can provide a layer of protection for the entrepreneur's personal assets, as the shares are held by the company rather than the individual.
Complexity and Costs
While a holding structure offers significant benefits, it also increases complexity. You will have two sets of accounts, two sets of tax returns, and additional administrative obligations. The costs of maintaining a holding structure must be weighed against the tax savings. For small businesses with low profits, the administrative burden may outweigh the benefits. However, for entrepreneurs with significant equity or multiple business lines, a holding structure can be a powerful tool for wealth preservation and growth. according to Step 8 End
When to Consider a Holding
Consider a holding structure if you plan to acquire other companies, if you have significant personal assets that you wish to protect, or if you intend to distribute dividends in a tax-efficient manner. The decision to set up a holding should be made in consultation with a tax adviser who can model the long-term tax implications. At Schmitz Tax Services, we help entrepreneurs evaluate whether a holding structure adds value to their specific situation, ensuring that the complexity is justified by the benefits.
Tax Compliance Administration: Ongoing Obligations
Setting up a BV or holding structure is only the beginning. Ongoing tax compliance is a continuous process that requires careful management of deadlines, filings, and records. Failure to comply with Dutch tax laws can result in penalties, interest, and even personal liability for directors. A robust administrative system is essential for maintaining a compliant business.
Core Tax Returns
A Dutch BV must file several tax returns each year. These include the corporate income tax return, VAT returns, and payroll tax returns if you have employees. Each return has its own deadline and specific requirements. The corporate income tax return is due five months after the end of the financial year. VAT returns are typically filed quarterly, and payroll tax returns are filed monthly. Missing a deadline can result in a penalty, even if no tax is due. A tax adviser monitors these deadlines and ensures that all returns are filed on time and in line with the rules.
Bookkeeping and Annual Accounts
Accurate bookkeeping is the foundation of tax compliance. For a BV, the annual accounts must be filed with the Chamber of Commerce within twelve months of the end of the financial year. These accounts form the basis for the corporate income tax return. Up-to-date records also prevent errors in VAT returns, which often only come to light at the year-end close. At Schmitz Tax Services, we provide full bookkeeping and annual accounts that keep your records current throughout the year, so the figures are usable when you need them rather than only afterwards.
Payroll and Employee Taxes
If you employ staff in the Netherlands, you are responsible for withholding and paying payroll taxes. This includes income tax, national insurance contributions, and other statutory deductions. Payroll administration can be complex, especially if you have employees in different locations or with different contract types. A tax adviser can help you set up a compliant payroll system and ensure that all deductions are calculated correctly. This reduces the risk of errors and penalties, allowing you to focus on your business operations.
Deadlines and Monitoring
Every return has its own deadline, and they do not run in parallel. The income tax return for a calendar year can be filed from 1 March of the following year and is generally due before 1 May. For corporate income tax, the deadline is five months after the end of the financial year. Filing late results in a penalty, even when there is nothing to pay. A tax adviser monitors these deadlines and will inform you in good time of what is still needed for them. This proactive approach ensures that you are never caught off guard by a missed deadline.
| Service | Key Obligations | Frequency | Deadline |
|---|---|---|---|
| Corporate Income Tax | Annual return for BV | Annual | 5 months after year-end |
| VAT | Quarterly return | Quarterly | 1 month after quarter-end |
| Payroll Tax | Monthly return for employees | Monthly | 1 month after month-end |
| Annual Accounts | Filing with Chamber of Commerce | Annual | 12 months after year-end |
Key Takeaways
- Choosing between a sole proprietorship and a BV is a critical decision that affects liability, tax, and administrative burden.
- A holding structure can provide tax advantages through the participation exemption but increases complexity and costs.
- Ongoing tax compliance requires careful management of deadlines, filings, and records to avoid penalties.
- Accurate bookkeeping is the foundation of tax compliance and ensures that your records are current throughout the year.
- The balance between salary and dividends is a key optimization area for BV directors.
- A tax adviser should analyze your business model and actual activities to determine the optimal structure and compliance strategy.
- Proactive monitoring of deadlines and filings is essential for maintaining a compliant business entity.
Frequently Asked Questions
When should I convert my sole proprietorship to a BV?
The timing of the conversion depends on your revenue, profit margins, and growth trajectory. Converting too early may result in unnecessary administrative costs, while waiting too long can complicate the transfer of assets and liabilities. A tax adviser can help you determine the optimal moment for incorporation based on your specific circumstances. according to Step 8 End
What are the tax advantages of a holding structure?
The primary tax advantage of a holding structure is the participation exemption, which exempts dividends received by the holding company from corporate income tax. This allows profits to be retained within the holding structure and reinvested without immediate tax leakage. Additionally, the holding structure can provide a layer of protection for the entrepreneur's personal assets.
How often do I need to file VAT returns?
VAT returns are typically filed quarterly in the Netherlands. The deadline for filing is one month after the end of the quarter. Missing a deadline can result in a penalty, even if no tax is due. A tax adviser can monitor these deadlines and ensure that all returns are filed on time.
What is the mandatory director's salary for a BV?
The mandatory director's salary is the minimum salary that a director of a BV must receive. This salary is subject to income tax and payroll tax. The exact amount depends on the size of the company and the director's role. The balance between salary and dividends is a key optimization area for BV directors.
Can I use accounting software for my BV's bookkeeping?
Yes, you can use accounting software for your BV's bookkeeping. However, it is important to ensure that the software is compliant with Dutch tax laws and that your records are accurate and up-to-date. A tax adviser can help you choose the right software and ensure that your records are in order.
What happens if I miss a tax deadline?
Missing a tax deadline can result in a penalty, even if no tax is due. The penalty amount depends on the type of return and the length of the delay. A tax adviser can help you avoid missed deadlines by monitoring them and ensuring that all returns are filed on time.
Do I need a tax adviser if I have a holding structure?
Yes, a tax adviser is highly recommended if you have a holding structure. The complexity of a holding structure increases the risk of errors and non-compliance. A tax adviser can help you manage the administrative burden and ensure that all tax obligations are met.
Conclusion
Setting up a BV, establishing a holding structure, and managing ongoing tax compliance are complex processes that require expert guidance. The right tax adviser can help you navigate these challenges and ensure that your business is structured for long-term success. Schmitz Tax Services offers the in-house quality large companies have, with a single point of contact for all your tax and administrative needs. Whether you are just starting out or looking to optimize your existing structure, we can help you make informed decisions that align with your business goals. To plan your visit, for a free introductory conversation.