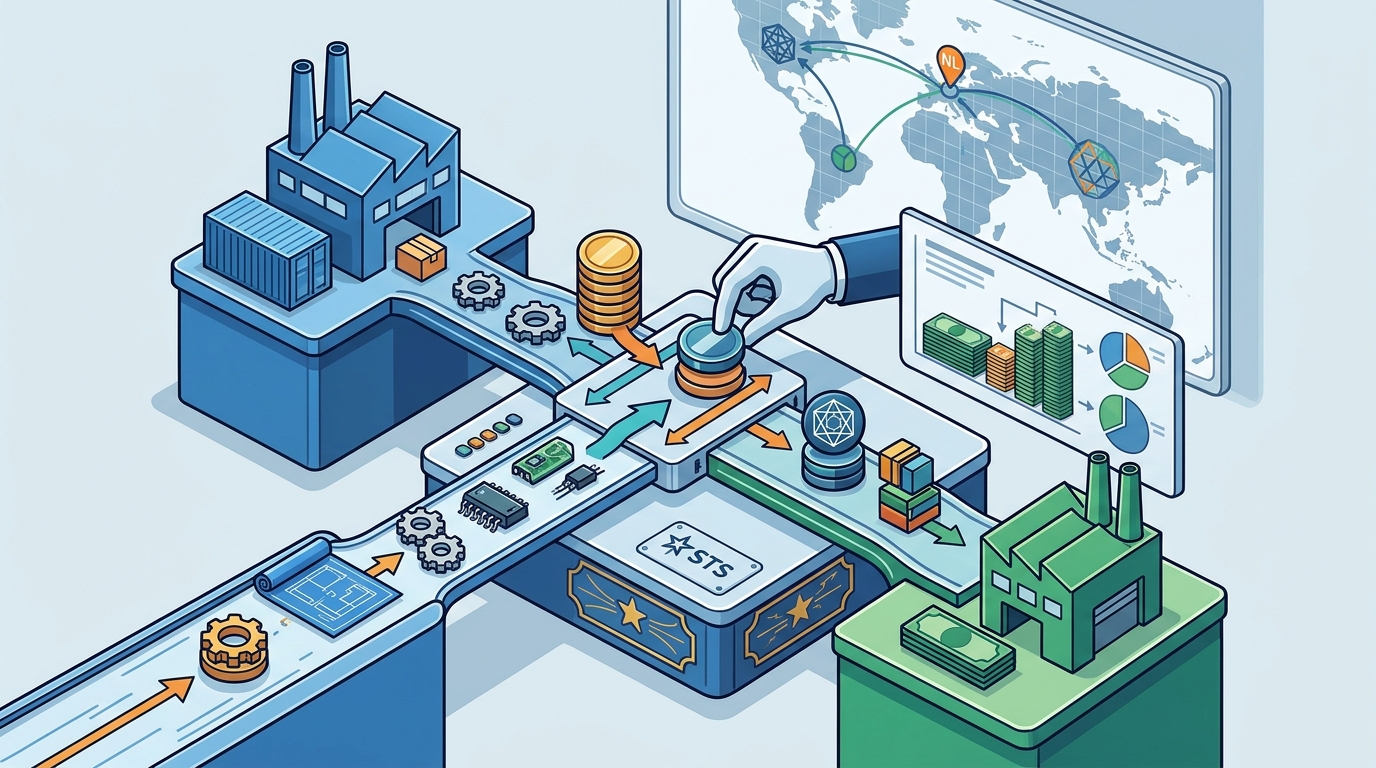
Transfer pricing is the determination of prices for goods, services, or intangibles exchanged between related parties in different tax jurisdictions. It directly affects your international business operations by determining how much profit is allocated to each entity, which in turn dictates the corporate income tax payable in each country. For Dutch business owners, getting this right is critical to avoid penalties and ensure compliance with the OECD guidelines.
Definition and Core Principles
At its core, transfer pricing is the process of setting prices for transactions between affiliated companies. The fundamental rule is the arm's length principle. This principle is the standard that requires related parties to transact as if they were independent entities dealing at arm's length. In practice, this means the price charged for a service or product must reflect what an unrelated buyer would pay in a competitive market.
The Organisation for Economic Co-operation and Development (OECD) provides the global framework for these rules. The OECD Transfer Pricing Guidelines for Multinational Enterprises and Tax Administrations serve as the primary reference for tax authorities worldwide. When the Dutch Tax Administration reviews a file, they look for evidence that the pricing aligns with this standard. If the price deviates significantly from market rates, the tax authority may adjust the profit allocation.
For a Dutch BV, this means that if you sell goods to a subsidiary in another country, the price cannot be artificially low to shift profit to a lower-tax jurisdiction. The profit must remain in the Netherlands if the Dutch entity is the one performing the valuable functions. Understanding this baseline is the first step in managing your international structure.
Impact on Dutch Business Owners
For entrepreneurs operating a Dutch BV with international clients or employees, transfer pricing rules have tangible financial implications. The impact is most visible in the corporate income tax return. If your Dutch entity provides management services to a foreign affiliate, you must charge a fee that reflects the market value of those services. This fee becomes taxable income in the Netherlands.
Consider a scenario where a Dutch holding company provides strategic oversight to an operating subsidiary in a low-tax country. If the holding company charges no fee, the Dutch tax authority may impute a fee. This imputed fee increases the taxable profit in the Netherlands. The result is a higher tax bill and potential interest charges. This is why documentation is not just a formality; it is a financial safeguard.
Furthermore, the rules affect how you structure your group. If you are moving from a sole proprietorship to a BV, or if you are adding a foreign entity to your group, the pricing of intercompany transactions must be established from day one. Schmitz Tax Services advises clients on these structural decisions to ensure the tax position is sustainable and defensible.
Documentation and Compliance Requirements
Compliance with transfer pricing rules requires robust documentation. The OECD guidelines outline a three-tier documentation system. The first tier is the Master File, which provides a high-level overview of the multinational group's business and transfer pricing policies. The second tier is the Local File, which contains detailed information about the specific transactions in the local jurisdiction.
The third tier is the Country-by-Country Report (CbCR). This report is required for large multinational groups with a consolidated revenue of EUR 750 million or more. It provides a breakdown of income, taxes paid, and economic activity by country. For smaller groups, the CbCR may not be mandatory, but the Master File and Local File requirements still apply if the group meets certain size thresholds.
Failure to maintain this documentation can lead to significant penalties. The Dutch Tax Administration can impose fines for non-compliance. Moreover, without proper documentation, you cannot defend your pricing positions in an audit. The documentation must be prepared before the tax return is filed. It is not a document you create after receiving a letter from the tax authority.
Common Pitfalls and Risks
One of the most common pitfalls is assuming that because two entities are related, the pricing is automatically correct. This is a dangerous misconception. Tax authorities in different countries may have different views on what constitutes an arm's length price. This can lead to double taxation, where both countries tax the same profit.
Another risk is the failure to update documentation when the business model changes. If your Dutch entity starts performing new functions, or if the market conditions shift, your transfer pricing analysis must be updated. A static document from three years ago may no longer reflect your current reality. This mismatch is a red flag for auditors. according to The World Eyes
Additionally, many business owners underestimate the complexity of intangible assets. If your Dutch entity owns intellectual property, the valuation of that IP and the royalties charged for its use are highly scrutinized. The profit from IP can be substantial, and tax authorities are keen to ensure it is taxed where the value is created. Getting this wrong can result in significant adjustments.
Strategic Considerations for Expats and Foreign Owners
For expats and foreign business owners with a Dutch BV, transfer pricing adds a layer of complexity to an already intricate tax situation. If you live abroad but own a Dutch BV, the interaction between your personal tax residence and the corporate tax position of the BV is critical. The rules on substantial shareholding and the allocation of management and control can influence how the BV's profits are treated.
It is essential to consider the tax treaties between the Netherlands and your country of residence. These treaties may provide relief from double taxation, but they also have specific provisions regarding the taxation of business profits. A misstep in transfer pricing can undermine the benefits of these treaties. For example, if the Dutch BV is deemed to be managed and controlled from abroad, the tax residence of the company may shift, with significant consequences.
At Schmitz Tax Services, we approach these situations from a business perspective. We analyze the actual activities, the flow of money, and the risks involved. This ensures that the tax position is not just compliant on paper but also sustainable in practice. We help you navigate the intersection of personal and corporate tax in a cross-border context.
Key Takeaways
- Transfer pricing is the setting of prices for transactions between related parties in different tax jurisdictions.
- The arm's length principle requires that these prices reflect what independent parties would agree to in a competitive market.
- Proper documentation, including the Master File and Local File, is mandatory for compliance and defense in audits.
- Incorrect pricing can lead to profit adjustments, higher tax bills, and potential double taxation.
- Business model changes require updates to transfer pricing documentation to maintain compliance.
- Foreign owners of Dutch BVs must consider the interaction between personal tax residence and corporate tax position.
Frequently Asked Questions
What is the arm's length principle in transfer pricing?
The arm's length principle is the standard that requires related parties to transact as if they were independent entities. It ensures that the price charged for goods or services reflects market value, preventing profit shifting to low-tax jurisdictions.
Do I need transfer pricing documentation if I am a small business?
How does the Dutch Tax Administration view transfer pricing?
The Dutch Tax Administration follows the OECD guidelines. They expect taxpayers to document their transfer pricing policies and apply the arm's length principle. They actively audit files where pricing appears to deviate from market norms.
What happens if my transfer pricing is challenged by a tax authority?
If a tax authority challenges your pricing, they may adjust the profit allocation. This can lead to additional tax, interest, and penalties. You can object to the assessment, but you must have strong documentation to support your position.
Can I use the same transfer pricing policy for all my countries?
While the OECD guidelines provide a global framework, local tax laws and interpretations can vary. It is important to ensure that your policy is compliant in each specific jurisdiction where you operate.
How does Schmitz Tax Services help with transfer pricing?
Schmitz Tax Services provides advice on the tax consequences of international structures. We analyze your business model and help you establish a defensible tax position, ensuring that your documentation aligns with your actual operations.
Conclusion
Transfer pricing is not just a technical accounting exercise; it is a strategic component of your international business operations. It determines where your profits are taxed and how much you pay. By understanding the arm's length principle and maintaining robust documentation, you can protect your business from unnecessary tax risks. For Dutch business owners and expats, the stakes are high, and the rules are complex. That is why professional guidance is essential.
At Schmitz Tax Services, we provide the clarity you need to navigate these rules. We work with you to ensure that your tax position is not only compliant but also aligned with your business goals. If you are operating a Dutch BV with international connections, it is time to review your transfer pricing strategy. to discuss how we can help you secure your international tax position.